A mobility scooter is something you rely on daily, whether that’s running errands, getting to appointments, or just moving around your neighborhood, so it makes sense to want it protected.
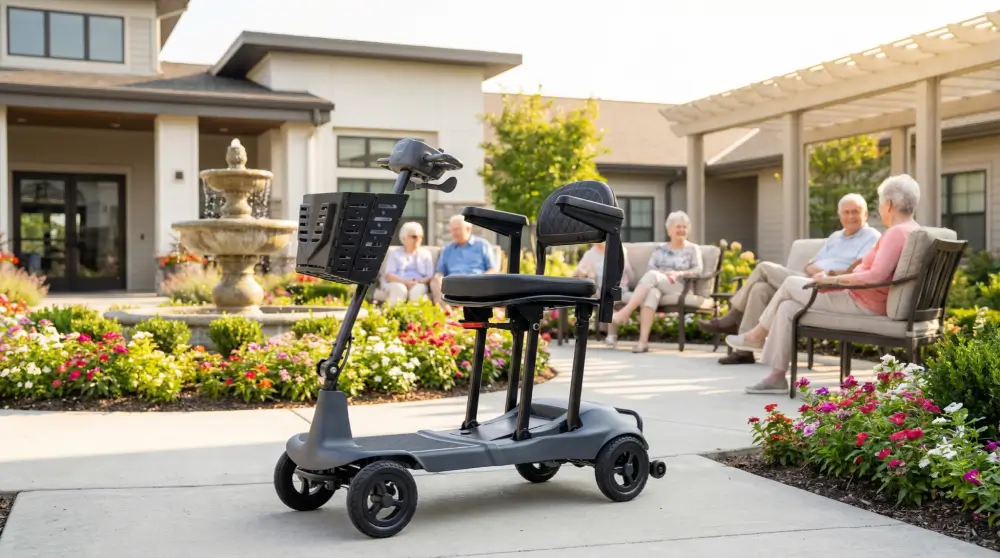
Mobility scooter insurance can help cover the cost of repairs, replacement, or liability if something goes wrong, one less thing to think about while you’re out and about. Here’s a clear, practical look at what this kind of coverage typically includes and how to go about getting it.
What Mobility Scooter Insurance Typically Covers
Coverage varies by provider and policy, but most mobility scooter insurance falls into two categories:
Property coverage protects the scooter itself. This can include reimbursement if your scooter is stolen, damaged in an accident, or damaged by something like fire or severe weather. Some policies also include coverage for accessories, such as baskets or travel bags.
Liability coverage protects you if you’re responsible for injuring someone else or damaging their property while operating your scooter. This kind of coverage can help with medical costs or repair expenses that result from an accident that wasn’t your intention but was still your responsibility.
Some policies bundle both types of protection together, while others let you choose just one. The right combination depends on how and where you use your scooter, and how much peace of mind you’re looking for.
Does Your Homeowners or Renters Insurance Already Cover You?
Here’s some genuinely good news: many standard homeowners and renters insurance policies already extend some protection to mobility scooters.
Most policies exclude “motor vehicles” from standard property coverage, but they typically carve out an exception for vehicles used to assist a person with a disability. Because mobility scooters are medical mobility devices, they often fall into this exception, meaning your scooter may already be covered under your existing policy’s personal property section, up to your policy limits and subject to your deductible.
That said, there are a few things worth checking with your insurance provider:
- Coverage limits. Standard personal property limits may not reflect the full value of your scooter, especially for higher-end models.
- Off-premises coverage. Some policies cover theft or damage only while the scooter is in your home, with reduced coverage if it happens elsewhere.
- Liability. Property coverage for the scooter itself doesn’t necessarily include liability coverage if you cause an accident while riding.
If any of these gaps apply to you, ask your insurance agent about adding a rider or scheduled personal property endorsement. This is a simple add-on that increases your coverage limit for a specific, named item, in this case your mobility scooter, and can sometimes reduce or waive your deductible for that item if a claim comes up.
Mobility Scooter Insurance vs. Medicare
The difference comes down to this: Medicare and private health plans help you get a scooter, while mobility scooter insurance protects the scooter once you have it.
Medicare Part B and many private health plans classify mobility scooters as durable medical equipment (DME). When a doctor determines a scooter is medically necessary, after an in-person evaluation and a written prescription, that coverage can help with the cost of the scooter itself. That’s the extent of it, though. Once the scooter is in your hands, this coverage stops. It generally won’t pay for theft, accidental damage, or liability if something happens while you’re out riding.
That’s where mobility scooter insurance comes in, covering the scooter itself and you as the rider through a separate policy or an endorsement added to a policy you already have.
When a Standalone or Specialty Policy Makes Sense
For most everyday use, a rider on your existing homeowners or renters policy is often enough. But a standalone mobility scooter or equipment insurance policy can be worth exploring if:
- You travel frequently with your scooter, whether by car, cruise, or plane, and want coverage that follows you outside the home.
- Your scooter represents a significant investment and you want dedicated, higher-limit coverage.
- You don’t currently have homeowners or renters insurance at all.
A licensed insurance agent can walk you through whether a standalone policy, an endorsement on your existing coverage, or a personal liability umbrella policy makes the most sense for your situation.
How to Get Mobility Scooter Insurance: Step by Step
Getting covered doesn’t have to be complicated. Here’s a simple path to follow:
- Call your current insurance agent first. Ask them directly what your existing policy already covers, rather than assuming either way.
- Gather your documentation. Keep your purchase receipt, model and serial number, and any photos of your scooter together in one place. It makes any follow-up conversation, or a future claim, go much faster.
- Decide what kind of coverage fits your situation. Based on what your agent tells you, weigh whether an endorsement on your current policy, a standalone policy, or an umbrella policy makes the most sense for how you use your scooter.
- Ask how the claims process actually works. Find out what documentation you’d need to file a claim and roughly how long it takes, so you know what to expect if you ever have to use it.
- Get it in writing. Once coverage is in place, request a copy of the updated policy or endorsement documents so you have clear proof of what’s covered.
Questions Worth Asking Before You Choose a Policy
A few good questions can help you find a policy that actually fits your needs. If a question comes up that’s more about the scooter itself than the policy, our FAQs page is a good place to look:
- Is my scooter covered for its full replacement value, or only its depreciated value?
- Will filing a claim affect my homeowners or renters premium?
- Is there a waiting period before coverage begins?
- Does the policy cover accessories, like a travel bag or basket, along with the scooter itself?
- How long does a typical claim take to process?
Getting clear answers up front means fewer surprises later, and more confidence every time you head out the door.
Protecting the Freedom Your Scooter Gives You
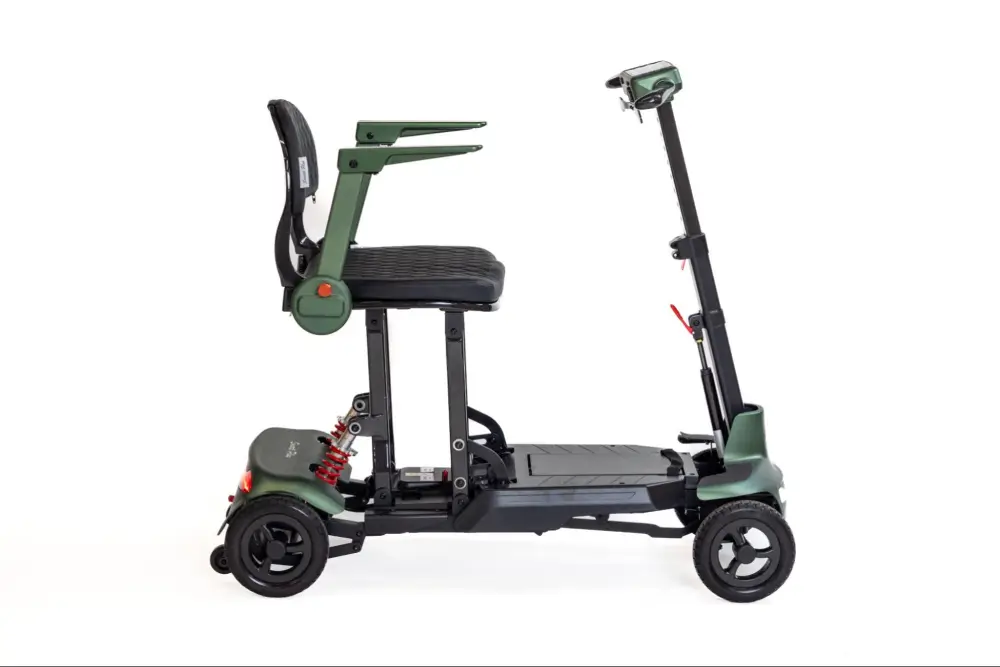
A mobility scooter is more than a piece of equipment. It’s what lets you get to appointments, run errands, and spend time with the people and places you care about on your own terms. Taking a few minutes to understand your insurance options is a small step that helps protect that independence for the long run.
If you’re still deciding on the right scooter for your lifestyle, our team can help you find a local dealer who can walk you through your options in person.
This guide is intended for general informational purposes and isn’t a substitute for advice from a licensed insurance professional. Coverage, terms, and availability vary by provider and by state, so confirm the specifics with your insurance agent before purchasing a policy.